Your 3% mortgage rate is crippling the housing market
Published in Business News
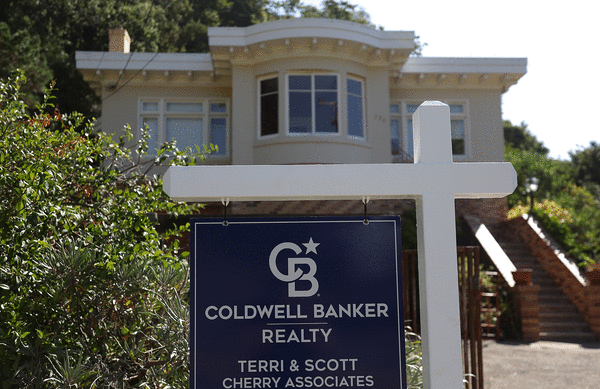
The U.S. housing market has been stuck in neutral for nearly four years, with sales of new and existing homes plodding along at a historically slow pace. One explanation is that the average rate on a 30-year fixed-rate mortgage in the U.S. passed 6% four years ago and has stayed above that ever since, creeping past 7% this week.
Mortgage rates above 6% did not stop Americans from buying and selling lots and lots of houses in past decades. What’s different now is that interest rates were much lower just a few years ago, leaving a yawning gap between the rates paid by homebuyers and those paid by existing homeowners. The gap hasn’t been this big since the early 1980s, and while it had been shrinking slowly since 2023, mortgage-rate increases this summer appear to have widened it again. Until it disappears, it’s hard to imagine the U.S. housing market returning to vibrant life.
The mortgage-rate gap “locks in” homeowners to their current low-rate mortgages and dwellings because selling and taking out a new mortgage to buy somewhere else carries a big financial penalty. Multiple recent economic studies have concluded that the disparity between market mortgage rates and those paid by existing homeowners sharply reduced moves and home sales after 2022.
The big question is how long this lock-in will last. A look back at the last time market mortgage rates exceeded the average rates paid by existing homeowners for such a long period offers some discouraging hints. In the early 1980s, high inflation and Federal Reserve Chair Paul Volcker’s quest to tame it drove interest rates to unheard-of levels. One result was that home sales, which I’ve adjusted here by the number of households in the U.S. to make the statistics more comparable over time, fell to their lowest rate on record in 1982. They didn’t stay that low for long, but one key reason they didn’t probably won’t apply this time around.
That reason was rapidly falling interest rates — by 1986 they were down more than 8 percentage points from their peak. Mortgage rates literally can’t fall that far this time and may not fall at all. What’s going on now with interest rates across the board could simply be a return to the pre-financial crisis norm, with the period of sub-6% mortgage rates from 2008 to 2022 looking ever more anomalous in the rearview mirror. That leaves replacing old mortgages with new mortgages as houses are bought and sold as the only mechanism by which the mortgage-rate gap and accompanying lock-in can be reduced. Which, given the current low rate of home sales, could take a while.
New construction helps, and homebuilders have been doing their part by reducing prices (in part by building smaller houses) even as existing-home prices continue to rise. For the first time on record, the median sales price is now lower for new single-family houses than for existing ones, seasonal variations aside. New houses remain only a fraction (15% of single-family home sales over the past 12 months) of the overall housing market, though.
Rapid income growth might also help move things along, as more buyers would be able to afford the higher financing costs. But even with U.S. median household income up 10% since 2019 after adjusting for inflation, housing affordability as measured by the National Association of Realtors is way down because of first the big home-price increases in 2021 and 2022 and then the mortgage-rate increases that followed.
All in all, it looks like a recipe for several more years of mortgage lock-in and disappointing home sales — and, as a result, reduced economic dynamism as American homeowners are discouraged from relocating to new jobs or downsizing when the kids move out.
This is not an inevitable feature of housing markets; it’s a byproduct of the U.S. residential mortgage system with its government-encouraged reliance on long-term, fixed-rate loans. Countries where most home loans have variable rates don’t have this problem (they do have others). Neither does Denmark, where long-term, fixed-rate mortgages predominate, but homeowners are able to buy back their mortgages at market rates. When mortgage rates go up, mortgage prices fall, so instead of being locked in by rising mortgage rates, Danish homeowners are able to take advantage of them, paying off existing mortgages at a discount and thus removing the financial penalty for selling a home and financing another at a higher interest rate.
Economists have been touting the advantages of Danish-style mortgage contracts for more than two decades with no signs that U.S. lenders are about to start offering them, but related approaches are gaining some traction here. One is mortgage assumability, in which the buyer can simply take over the current homeowner’s low-rate mortgage — which doesn’t directly protect sellers from a big increase in mortgage rates if they buy another house but does presumably allow them to demand a higher sales price. This already exists in the U.S. for the 23% of outstanding mortgages backed by the Federal Housing Administration, Department of Veterans Affairs and Department of Agriculture, and the number of mortgage assumptions more than doubled in 2023 but still represented only a minuscule share of home sales.
Mortgage portability allows sellers to take their low rates with them and is offered in Canada and several European countries but not the U.S. Federal Housing Finance Agency Director Bill Pulte made headlines late last year by saying his agency was “actively evaluating portable mortgages,” and Michigan Republican Tom Barrett introduced a bill in the House in March calling for a study of them. But action has so far been lacking, and even if that changed, only new mortgage contracts would be portable, meaning the effect might not be felt until the next time mortgage rates suddenly jump by several percentage points, which going by the historical record could be 40 years from now. That means the only thing that can shake the U.S. housing market out of its doldrums may be the passage of time.
©2026 Bloomberg L.P. Visit bloomberg.com/opinion. Distributed by Tribune Content Agency, LLC.
Comments